
VAT and Invoicing on Manpower Supply in Saudi Arabia: What ZATCA Requires
ZATCA FATOORA Phase 2 e-invoicing rules, 15% VAT calculation on manpower supply, disbursements vs. service fees, and timesheet reconciliation.
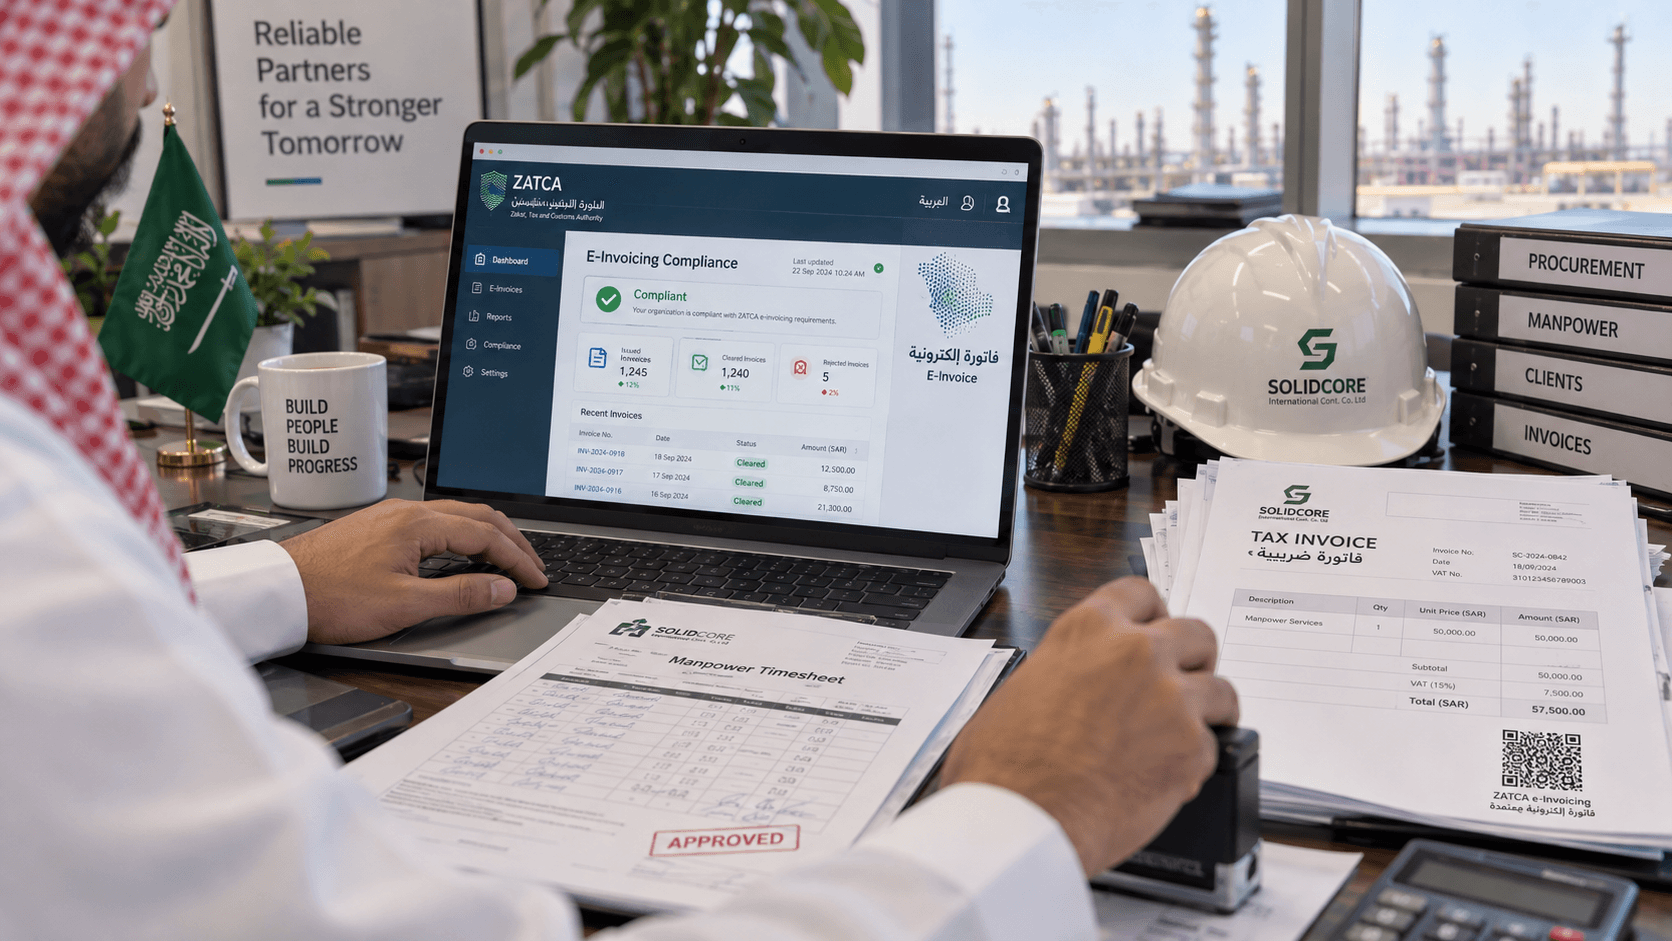
Manpower supply in Saudi Arabia is subject to the standard 15% Value Added Tax (VAT) administered by ZATCA, applied to the full invoiced service fee. Suppliers already in ZATCA's Phase 2 (integration) wave must issue e-invoices that meet its technical requirements, and the invoice should tie back to approved timesheets.
Key takeaways
- Manpower supply services are subject to the standard 15% VAT rate on the total gross invoice consideration.
- Under Phase 2 (integration), which ZATCA rolls out to taxpayers in waves, standard tax invoices between businesses are cleared through ZATCA's platform.
- Disbursements can only be excluded from VAT if they meet strict ZATCA pass-through agency criteria; labor costs cannot be treated as disbursements.
- Supervisor-signed timesheets and an agreed cut-off date prevent most invoice disputes.
Need these workers on your site?
Gulf Orbit supplies manpower and scaffolding to companies across Saudi Arabia. Pick the page closest to your requirement:
Standard 15% VAT on manpower supply services
In the Kingdom of Saudi Arabia, the supply of manpower and technical personnel is classified as a taxable supply of services under the Value Added Tax (VAT) Law administered by the Zakat, Tax and Customs Authority (ZATCA). The standard VAT rate of 15% applies to the total fee charged by the supplier to the client contractor.
A frequent question is whether VAT applies to the whole hourly or monthly rate, or only to the supplier's margin. Under ZATCA regulations, because the manpower supplier acts as an independent contractor providing services under a commercial contract, VAT is calculated on the entire gross contract price, including base labor wages, overtime, allowances, accommodation, and transportation billed to the client.
The same treatment applies wherever in the Kingdom the crew works, for example manpower supply in Riyadh or manpower supply in Dammam.
Pure manpower supply vs. expense reimbursements (Disbursements)
Pass-through costs, such as travel tickets, gate pass fees or medical tests, cause disputes because ZATCA separates taxable parts of the service from genuine disbursements.
| Invoice Line Item | VAT Rate | ZATCA Treatment | Substantiation Required |
|---|---|---|---|
| Base Labor Rate (Hourly / Monthly) | 15% Standard | Taxable service consideration | Signed and client-approved timesheets with supervisor signature |
| Overtime Hours (1.5x / 2.0x) | 15% Standard | Taxable service consideration | Overtime logs matching Saudi Labor Law Article 107 provisions |
| Mobilisation / Demobilisation Fees | 15% Standard | Taxable ancillary service charge | Mobilisation manifests, travel waybills, and gate pass records |
| Accommodation & Transport Allowances | 15% Standard (if billed by supplier) | Integral component of service price | Contractual agreement terms and rate breakdown schedule |
| Pure Pass-Through Disbursements | Out of Scope / Passed at Cost (Rare) | Must meet ZATCA's disbursement conditions (cost incurred in the client's name, passed on at cost) | Original third-party tax invoice attached; rarely valid for standard labor costs |
ZATCA FATOORA Phase 2 e-invoicing for B2B contractors
Under ZATCA's Phase 2 (integration), taxpayers selected in each wave connect their billing systems to ZATCA's FATOORA platform. Once a supplier is in scope, an invoice produced outside that system is not a valid tax invoice for input VAT. Ask your supplier whether it has been brought into Phase 2 yet.
A Phase 2 tax invoice carries: - Cryptographic Stamp (CS): A digital signature proving invoice authenticity and integrity. - Invoice Hash: A unique alphanumeric cryptographic string connecting the invoice to preceding transactions. - Universally Unique Identifier (UUID): A distinct identifier generated by the billing system. - QR Code: Containing encoded seller information, VAT registration number, timestamp, total invoice amount, and cryptographic signature. - ZATCA Clearance / Reporting Stamp: Proof that the invoice was electronically submitted and validated by the ZATCA portal.
An invalid invoice can cost you the input VAT deduction at audit.
Timesheet reconciliation, overtime, and invoice substantiation
Most invoice disputes in manpower supply come from timesheets. A fixed billing cycle avoids them:
1. Daily Sign-Off: The contractor's work front supervisor signs daily timecards confirming regular hours and approved overtime for each craft role. 2. Weekly Summary Consolidation: The supplier compiles weekly summaries cross-checking hours against project work orders and gate pass logs. 3. Monthly Cut-Off & Reconciliation: On the agreed cut-off date (e.g., the 25th of each month), both parties reconcile total hours before an electronic tax invoice is generated. 4. Overtime: Article 107 of the Saudi Labour Law sets overtime pay at the hourly wage plus 50% of the basic wage. Work on rest days and official holidays is treated as overtime. How overtime is billed to you is a commercial term, so agree it in the contract.
Invoice defects that delay payment
Finance teams hold invoices for avoidable reasons:
- Mismatched Purchase Order (PO) Numbers: Invoices generated without referencing the correct client PO number or contract schedule. - Missing Timesheet Attachments: Invoices submitted without client-signed physical or digital timecards. - Incorrect Entity Legal Names or VAT Numbers: Discrepancies between the Commercial Registration name and the invoice header. - Premature Invoicing Before Ajeer Notice Confirmation: Billing for labor prior to the confirmed issuance date of the statutory Ajeer notice.
To see how a manpower quotation is structured line by line, read the pricing guide, or send an RFQ through the manpower request form.
*Tax Note: This article provides operational guidance for contractors in Saudi Arabia and does not constitute formal tax or legal advice. Specific tax questions should be directed to certified tax advisors and validated against current ZATCA guidelines (Last reviewed: September 2026).* For the terms used here, see the glossary.
Frequently asked questions
Is VAT charged on the worker's salary portion or the entire manpower rate?
VAT is applied to the total gross invoice amount charged by the manpower supplier, which includes the base wage, overhead, allowances, and profit margin. Under ZATCA rules, labor supply cannot be broken down into exempt and taxable components.
Can our company claim input VAT deduction on manpower supply invoices?
Yes, if your company is VAT registered in Saudi Arabia and the supplier issues a valid tax invoice with its VAT number. If the supplier is in a Phase 2 wave, the invoice must also meet Phase 2 requirements.
What if a supplier's invoice does not meet Phase 2?
If the supplier is in scope for Phase 2 and the invoice does not meet it, the input VAT can be disallowed at audit. Ask the supplier to reissue a compliant invoice before you pay.
How should timesheet reconciliation and invoice substantiation be handled?
Agree it in the contract: timesheets signed off by your site supervisor, and each monthly tax invoice referencing the approved timesheets and the PO number. Gulf Orbit is VAT registered with ZATCA. State your own invoicing requirements in the RFQ so they are agreed before mobilization.